Can you really tap your Rancho Cucamonga home equity to buy a luxury property in North Etiwanda or Alta Loma before your current home sells?
Yes. With a bridge loan, a HELOC, or a hybrid of both, you can fund the down payment on a foothill estate, submit a non-contingent offer, and sell your current home on your own timeline.
*Disclaimer: This post is informational only and does not constitute financial, tax, or legal advice. Consult a licensed lender and a CPA before acting on any strategy discussed here.*
Why This Matters Right Now for Rancho Cucamonga Move-Up Buyers
If you own a home in Victoria, Terra Vista, south Rancho Cucamonga, Upland, Ontario Ranch, or Fontana, the last five years have likely built you a serious equity cushion. As of June 2026, the median home sale price in Rancho Cucamonga is approximately $826,000, at roughly $408 per square foot, with homes selling in a median of 26 days, according to local MLS data. Home values across Rancho Cucamonga are up approximately 18.8% over the past five years (per 2026 market reporting). That appreciation is your bridge to the foothills.
But we need to talk about rates honestly. The Freddie Mac Primary Mortgage Market Survey placed the 30-year fixed at around 6.09% the week of February 12, 2026. If you locked in at 3% or 4% years ago, giving that up is a real, calculable cost. For some families, the land, the views, and the school districts of North Etiwanda and Alta Loma make the math work. For others, it may not pencil right now. With 8 years of experience and over 105 transactions closed in this market, what we always tell our clients is: let us run both scenarios with you before you commit to anything.
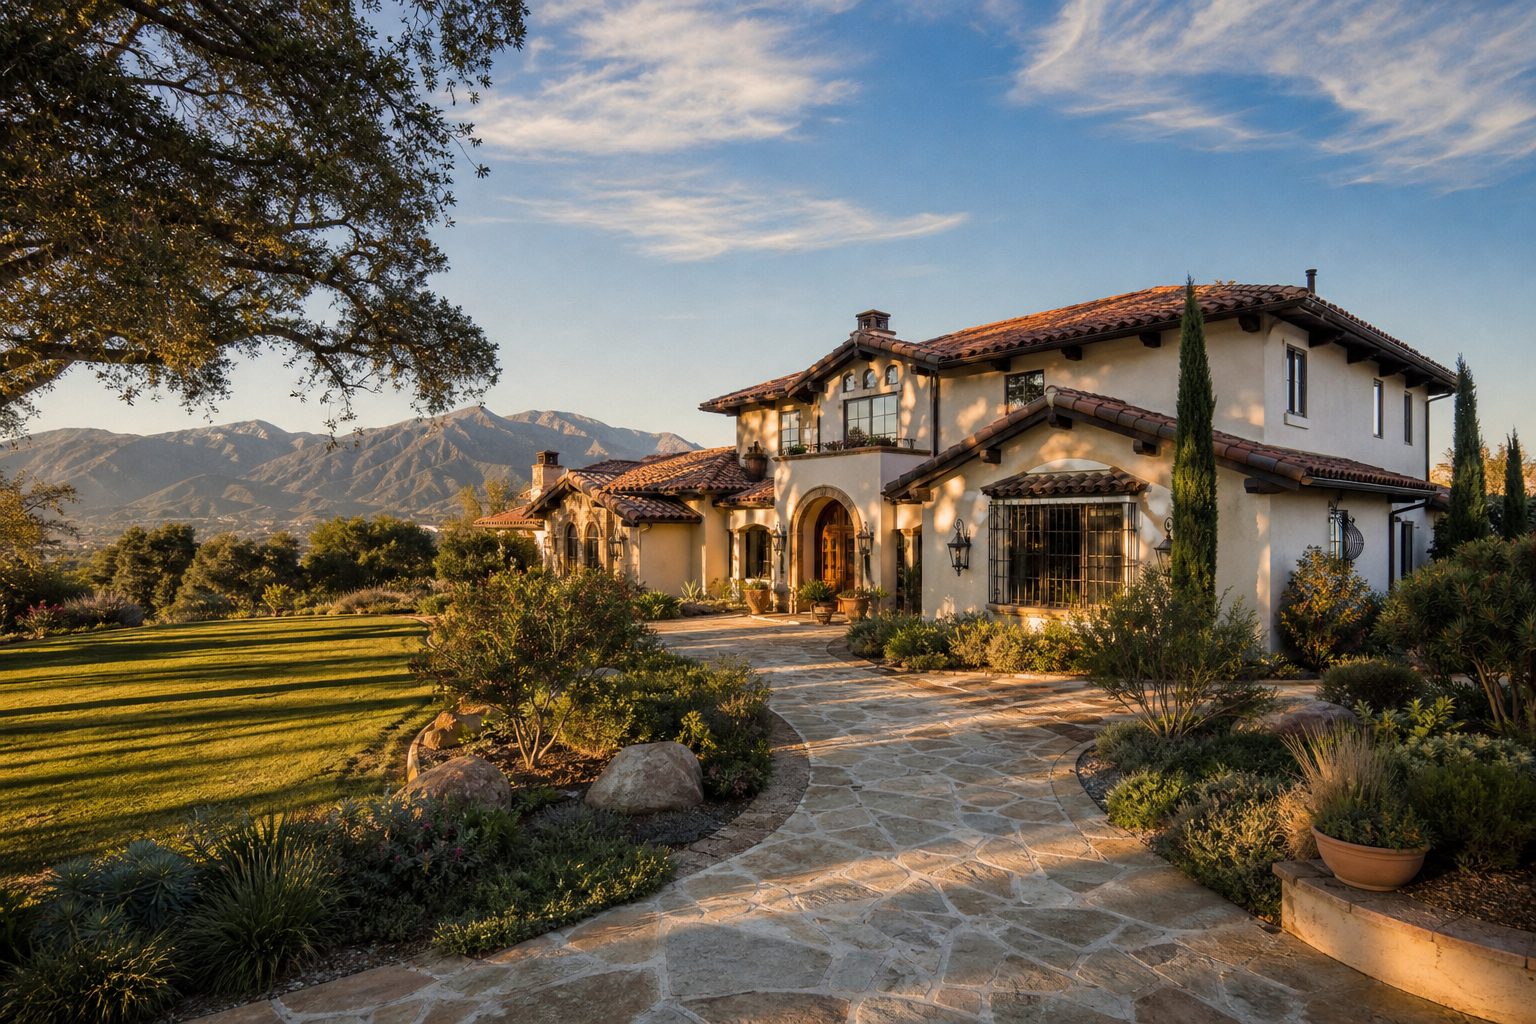
Here is what you are moving toward. In September 2026, Etiwanda homes were listed at a median price of approximately $1.4 million, or $434 per square foot. For Alta Loma, the median listing price came in at approximately $1.08 million as of June 2026. Estate homes in North Etiwanda and upper Alta Loma sit well above those medians, with data from late 2025 placing the North Etiwanda neighborhood closer to $1,288,000.
The traditional path of selling first, renting, then buying forces a double move and temporary housing costs. There is a better sequence.
Why North Etiwanda and Alta Loma in Rancho Cucamonga Are Worth the Move-Up
Foothill and luxury communities like Deer Creek, Haven View Estates, and Carriage Estates sit well above the citywide median, according to local market data, and for good reason. These are not just bigger houses. They offer a fundamentally different lifestyle.
North Etiwanda sits at the base of the San Gabriel Mountains along East Avenue and Day Creek Boulevard. Estate lots routinely run half an acre to over an acre. You get panoramic mountain views, quiet streets off Etiwanda Avenue and Wilson Avenue, proximity to the North Etiwanda Preserve (a 1,500-acre open space with equestrian and hiking trails), and quick SR-210 and I-15 access that puts you at the Ontario Airport employment corridor in under 20 minutes.
Alta Loma runs north along Carnelian Street, Archibald Avenue, and Hellman Avenue toward Baseline Road and into the foothill zones. Several Alta Loma areas fall within an Equestrian/Rural Overlay and connect to community bridle trails, with Heritage Park serving as a local equestrian hub. Many Alta Loma addresses sit a short drive from foothill trailheads serving the North Etiwanda Preserve and Etiwanda Falls.
Schools drive families to these communities. Etiwanda High School (13500 Victoria St.) holds an overall A grade on Niche for 2026 and ranks number 6 among the best public high schools in San Bernardino County, per Niche. The Etiwanda Elementary School District holds an overall A- Niche grade for K through 8. Multiple Alta Loma Elementary School District schools also hold A- Niche grades, with Alta Loma Elementary offering a Gifted and Talented program rated as performing above average compared to California public and charter schools.
Your family deserves the best. That is not a slogan; it is why we specialize in coordinating both sides of an upsizing move so you land in the right neighborhood for your next chapter.
Bridge Loans for Rancho Cucamonga Move-Up Buyers: How They Work
A bridge loan is a short-term loan secured by your current home. The lender uses your existing equity to fund the down payment on the new purchase. Once your old home sells, the bridge loan is paid off.
In 2026, here are the ranges you should expect:
- Rates: Approximately 9.5% to 11% from private lenders
- Origination fees: 1 to 3 points
- Structure: Interest-only payments
- Term: Typically 6 to 12 months, often with extension options
- Speed: Many close in 2 to 4 weeks
*Rates are current as of publishing. Get live quotes from multiple lenders before committing.*
An Illustrative Rancho Cucamonga Example
These figures are estimates for illustration only:
- Current Victoria-area home value: $850,000
- Remaining mortgage balance: $350,000
- Available equity at 80% CLTV cap: ($850,000 x 80%) minus $350,000 = $330,000
- Target purchase in North Etiwanda: $1,600,000
That $330,000 becomes your down payment. At a 10% bridge rate on $330,000, interest-only payments run roughly $2,750 per month. Carrying the bridge for four to six months costs between approximately $11,000 and $16,500 in interest, plus origination. Compare that to four to six months of a short-term rental at Inland Empire prices, storage fees, and two professional moves. For most families, the bridge costs less than the chaos.
HELOCs in Rancho Cucamonga: The Flexible, Lower-Cost Option
A HELOC is a revolving line of credit secured by your current home. You draw only what you need, and you pay interest only on what you draw.
Key details for 2026:
- Rates: Variable, tied to the prime rate. Many lenders cap CLTV at 80%.
- Setup time: Typically 3 to 6 weeks
- Flexibility: Draw, repay, redraw during the draw period
Here is the critical timing tip we share with every move-up client: open the HELOC before you list your home for sale. Many lenders will not open a HELOC on a property that is already actively listed. If you wait, you lose this option entirely. Plan ahead by 60 to 90 days.
A HELOC gives you flexibility a bridge loan does not. You can draw a portion for earnest money, draw more for the down payment at closing, and repay it all when your departing home sells. The lower rate compared to a bridge loan makes this attractive when timing allows.
The Hybrid Strategy: HELOC Plus Bridge Loan for Rancho Cucamonga Buyers
Sometimes neither tool alone is enough. Here is when a hybrid approach makes sense:
- Open a HELOC 60 to 90 days before you start shopping. This gives you a flexible, lower-cost first layer of capital.
- Layer a smaller bridge loan on top if needed. Because the HELOC handles part of the down payment, the bridge loan is smaller, which means lower total interest cost.
Other options worth a brief mention: contingent offers (generally weaker for desirable North Etiwanda and Alta Loma estates where sellers receive multiple non-contingent offers), cash-out refinance (usually less attractive given current rates because you replace your existing low rate on the full balance), and rent-back agreements where you negotiate to stay in your current home briefly after selling.
Jumbo Financing When Buying Luxury Homes in Etiwanda and Alta Loma
San Bernardino County’s 2026 conforming loan limit is $832,750. Most North Etiwanda and upper Alta Loma estate-style homes will exceed that, meaning you will need a jumbo loan for the new purchase.
Jumbo lenders typically require:
- Higher credit scores: 720 or above for the best pricing
- Larger reserves: Often 6 to 12 months of payments in liquid assets
- Lower debt-to-income ratios: Carrying two properties temporarily affects your DTI, so this must be planned
We work with jumbo lenders who understand simultaneous transactions in the Inland Empire. Having closed over 105 transactions, with $87 million in total volume and a 104% list-to-sale ratio, we bring the lender relationships that make underwriting smoother when you are temporarily carrying two properties.
Qualification Checklist Before You Start
- Equity: Ideally 20% or more in your current home
- Credit score: 680 minimum; 720 or above for best bridge and jumbo pricing
- DTI capacity: Your income must support both homes temporarily
- Reserves: Liquid savings beyond the down payment
- A marketable departing home: Your current home needs to be competitive when it hits the market
Selling Your Rancho Cucamonga Home the Right Way After You Move Up
This is the second half of the plan, and it is where the strategy pays dividends. Once you have moved into your Etiwanda or Alta Loma home, your departing property can be vacated, repaired, cleaned, and professionally staged. A vacant, staged home shows better, photographs better, and typically sells faster and for more.
We coordinate the sale timeline, pricing strategy, and marketing, including professional photography, video, social media launch, and outreach to our buyer interest list, before the purchase offer goes in. The goal is to keep the bridge period as short as possible. As of June 2026, Rancho Cucamonga homes are selling in a median of 26 days, per MLS data. Our average sits at approximately 13 days on market, which directly reduces your carrying costs on the bridge.
Our clients have experienced this firsthand. As one past client put it: “We recently decided to sell our home and purchase another one. With the type of house my family was looking for, we anticipated having to submit an offer without completing the sale of our current home first. Brent expertly navigated the process for us. Although the house we wanted had multiple offers, our offer was ultimately accepted. Furthermore, Brent got our old home on the market within a couple weeks. We had a busy open house weekend and received 2 offers within a few days. We eventually accepted an offer above asking price and closed escrow in under 30 days.”
That is the sequence working exactly as designed. Rated 4.9 out of 5 stars across 46 client reviews, we build our practice around protecting families through exactly this kind of high-stakes, time-sensitive transaction.
Frequently Asked Questions About Buying Before You Sell in Rancho Cucamonga
How much equity do I need to bridge into an Etiwanda luxury home?
Most bridge lenders cap at 80% combined loan-to-value on your current home. If your home is worth $850,000 and you owe $350,000, you could potentially access up to $330,000. Whether that is enough depends on the purchase price and your other liquid assets. We run these numbers with you before any commitment.
What are bridge loan rates in Rancho Cucamonga in 2026?
Private bridge lenders are quoting approximately 9.5% to 11% as of late 2026, with 1 to 3 points in origination. These are short-term rates designed for a 4 to 12 month hold. Rates change frequently, so get a live quote from your lender.
Is a HELOC or a bridge loan better for buying before I sell?
A HELOC is cheaper (lower rate, no origination fee in many cases) but takes 3 to 6 weeks to set up and must be opened before your home is listed. A bridge loan is faster and works even after listing. Many buyers use a hybrid of both.
Can I open a HELOC after I have already listed my home for sale?
Most lenders will not open a HELOC on a property that is actively listed. This is the number one timing mistake we see. If you think you may need a HELOC, open it 60 to 90 days before you plan to list.
What if my current home takes longer than expected to sell?
Bridge loans typically have 6 to 12 month terms with extension options. A well-priced, well-marketed home in Rancho Cucamonga is selling in a median of 26 days as of June 2026, per MLS data, so extended bridge periods are uncommon when the pricing strategy is right.
Will I need a jumbo loan for a home in North Etiwanda?
Almost certainly. San Bernardino County’s 2026 conforming limit is $832,750, and most North Etiwanda and upper Alta Loma estates list well above that. Jumbo qualification requires higher credit, larger reserves, and careful DTI management.
Should I give up my low mortgage rate to move up?
This depends on your specific numbers. Giving up a 3% or 4% rate is a real cost. We run a side-by-side comparison of your monthly payment increase against the lifestyle gains and long-term equity potential of the foothill home. For some families, the move makes sense now; for others, waiting is the right call.
Are there tax implications to tapping home equity for a move-up purchase?
Potentially. Interest deductibility rules, capital gains exclusions on your departing home, and property tax reassessment (under California Proposition 19) all matter. We always recommend you consult a CPA before finalizing any equity-based strategy.
Can I make a non-contingent offer without being a cash buyer?
Yes. A bridge loan or HELOC funds your down payment so you can remove the sale contingency from your offer. This makes your offer significantly more competitive on desirable North Etiwanda and Alta Loma properties where sellers receive multiple offers.
What is a rent-back agreement and could it help me?
A rent-back lets you sell your current home and remain in it as a tenant for a negotiated period, usually 30 to 60 days. This can reduce or eliminate the need for bridge financing, but it depends on your buyer agreeing to the terms. It works best as a backup plan, not a primary strategy.
The Bottom Line on Buying Before You Sell in Rancho Cucamonga
Moving up to North Etiwanda or Alta Loma without selling first is possible with the right sequence: secure your financing, make a non-contingent purchase offer, close on the new home, then sell your departing home vacant, staged, and on your terms. The equity you have built over the past five years, with Rancho Cucamonga values up 18.8% over that period, is the fuel.
We coordinate both sides of the transaction so the bridge period stays short and your family moves once. With 8 years of specialized experience in Rancho Cucamonga, over 105 transactions closed, and a track record of selling homes 60% faster than the local average, we build every move-up plan around one principle: your family deserves the best.
Ready to find out what your current home is worth and how much equity you can access? Call Brent Blay at 909-641-8751 or reach us at soldbyblay.com for a private move-up strategy session. We will walk you through both transactions, start to finish.
Your family deserves the best.

Leave a Reply