What do luxury buyers and sellers in Rancho Cucamonga’s foothill neighborhoods need to know about wildfire risk and homeowners insurance in 2026?
Fire hazard zone status and insurance availability are now the two most decisive variables in any Rancho Cucamonga foothill luxury transaction. If you are buying or selling a home north of the 210 Freeway in Alta Loma or Etiwanda, both must be confirmed before you write an offer, and both directly shape a seller’s pricing strategy.
Why Wildfire Insurance in the Rancho Cucamonga Foothills Matters Right Now
We approach fire risk the same way we approached emergency calls during our seven years on the ambulance: calmly, methodically, and with zero room for guesswork. Rancho Cucamonga falls within the very high fire hazard severity zone, per CAL FIRE designations. Living near the foothills of Rancho Cucamonga means facing a higher chance of experiencing a wildfire, according to local fire risk assessments.
North of the 210 Freeway, especially in Alta Loma and Etiwanda, wildfire exposure is a documented reality. The Cajon Pass wind corridor creates high-velocity gusts that push fire behavior in ways that make these foothills particularly vulnerable. The 2003 Grand Prix Fire advanced toward the Alta Loma foothills, burning thousands of acres in San Bernardino County, and that history is exactly why CAL FIRE designates this area the way it does.
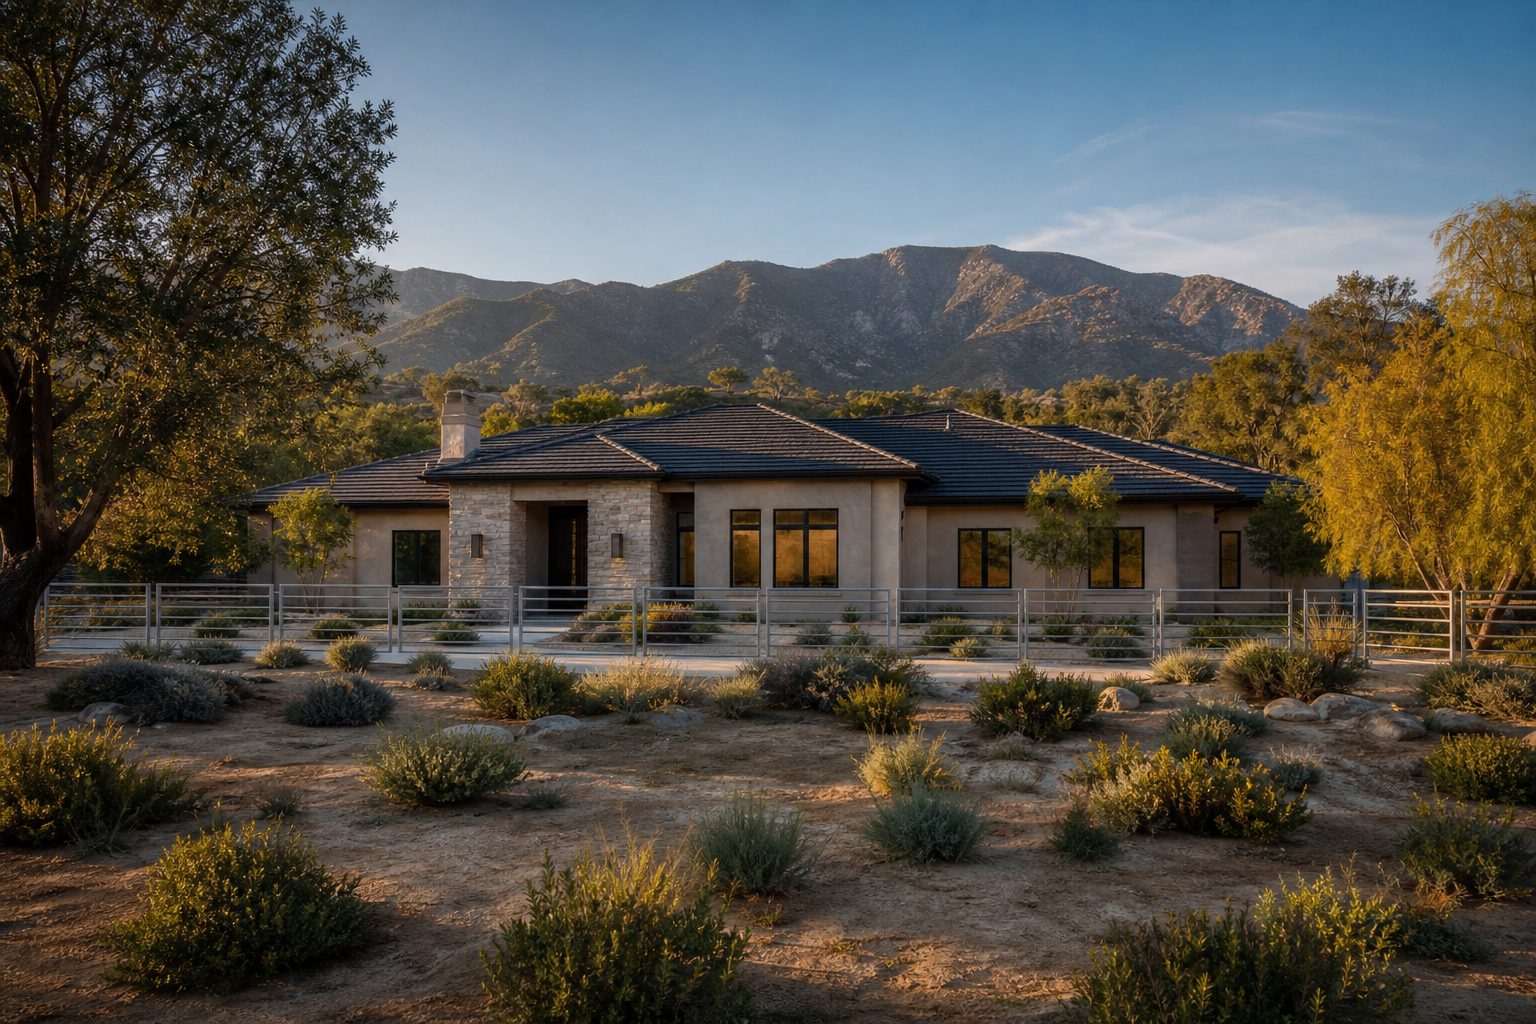
Here is the price context that makes insurance so urgent. Alta Loma north of 19th Street runs from roughly $1M to $2.5M and above on equestrian lots, while Etiwanda and Heritage-area homes run approximately $900K to $1.6M, according to recent listing data. Estate homes near the open space above those corridors, on streets like Almond, Thoroughbred, Wardman-Bullock Road, and up toward Sapphire Street near Cucamonga Canyon, sit well above both of those medians. When you are looking at a $1.5M to $4M property and a buyer cannot secure adequate fire insurance, escrow falls apart. With 105 closed transactions and 8 years in this market, we have seen that scenario unfold. It is preventable, but only if you plan ahead.
Rancho Cucamonga’s Updated Fire Hazard Severity Zone Map
The Fire Hazard Severity Zone Local Responsibility Area map was made available for public review and comment beginning on April 8, 2025, in accordance with California Government Code Section 51178.5, per the Rancho Cucamonga Fire Protection District. You can view the map online or at Fire Headquarters, located at 10500 Civic Center Drive, Rancho Cucamonga, during normal business hours.
Two important things to understand about these maps:
- State law prohibits the Fire District from assigning a fire hazard severity zone that is less restrictive than the one recommended by the State Fire Marshal. The Rancho Cucamonga Fire District is not proposing any additions or increases in the LRA FHSZ during this adoption process, according to the district’s own public notice.
- The maps will never get more lenient. They can only stay the same or become more restrictive.
According to CAL FIRE, the determination of “hazard” is based on the physical conditions that create a likelihood and expected fire behavior over a 30- to 50-year period, without considering mitigation measures such as home hardening, recent wildfire, or fuel reduction efforts. In other words, the zone reflects the landscape, not what you have done to your house. Home hardening matters enormously for insurance and safety, but it will not change your official zone designation.
You can enter your address on the OSFM map viewer to locate your property’s specific Fire Hazard Severity Zone. We recommend every buyer do this before making an offer, and every seller do it before pricing their home.
What Very High Fire Hazard Severity Zone Status Means for Your Property
- Defensible space compliance is legally required and enforced at sale under AB 38
- WUI Building Standards (Chapter 7A) apply to new construction and significant remodels, including ember-resistant vents, ignition-resistant materials, and more
- Insurance underwriting becomes harder and more expensive. Some traditional carriers will not quote a VHFHSZ property at all
- Natural Hazard Disclosures must reflect the designation, which affects buyer psychology and negotiation leverage
The California Insurance Reality for Rancho Cucamonga Luxury Homes
The California FAIR Plan, which stands for Fair Access to Insurance Requirements, was created by the state legislature in 1969 for homeowners in high-risk areas who have been turned down by regular insurance companies, according to the California Department of Insurance. It was far more expensive than standard insurance, and it covered less.
Now it is about to get more expensive still. The California Department of Insurance approved a 29.1% average rate increase statewide for the FAIR Plan, effective October 15, 2026, according to the Department of Insurance. The 29.1% is a statewide average. For policyholders with significant wildfire exposure, the increase to that portion of their premium could be far higher. Some will see their wildfire premiums double.
As of June 2026, the FAIR Plan’s total exposure is $768 billion, reflecting an 11% increase, per the Department of Insurance.
The Luxury Coverage Gap in Alta Loma and Etiwanda
The FAIR Plan’s residential coverage caps at $3.3 million and covers only named perils: fire, lightning, smoke, and internal explosion. For a $2.5M estate home in North Alta Loma, that cap may technically cover the dwelling, but you will have no coverage for theft, liability, water damage, or personal property. You will likely need a Difference in Conditions (DIC) policy or excess surplus-lines coverage to fill those gaps, and those policies carry their own premiums.
What does this actually mean for your budget? It means that a buyer looking at a $2M foothill home may be looking at $15,000 to $25,000 or more annually in combined fire and supplemental insurance costs, depending on the property’s specific risk score, hardening status, and replacement cost. That cost gets factored into debt-to-income ratios by lenders, potentially reducing the loan amount a buyer qualifies for.
Why Buyers Fall Out of Escrow in Fire Zones
This is where things get real for sellers. When a buyer’s insurance quote comes back higher than expected, it can cascade into several deal-breaking problems:
- Affordability shock. Higher insurance rates combined with elevated mortgage rates and rising home prices push total monthly costs beyond what the buyer budgeted
- Debt-to-income ratio issues. Lenders factor insurance into qualifying ratios. A $1,500 per month insurance bill, versus a projected $400, can disqualify the buyer entirely
- Coverage unavailability. Some buyers simply cannot find a carrier willing to write a policy for a specific parcel, leaving them without the coverage their lender requires
- Buyer cold feet. Even cash buyers, who have no lender mandate, sometimes walk when they see the true cost of insuring a foothill home
We tell our clients this upfront because we have seen every one of these scenarios. Having closed over 105 transactions in the Rancho Cucamonga area with a 104% list-to-sale ratio, we know that proactive insurance planning is what separates deals that close from deals that collapse at the 11th hour.
What to Do If You Have Been Dropped by Your Insurance Company
If your carrier has non-renewed your policy, do not panic, and do not go directly to a single company like a large national brand. Instead, reach out to an independent insurance broker. Brokers have access to multiple carriers and surplus-lines markets, and they will do the heavy lifting of comparing coverage options for you. We maintain a network of vetted insurance brokers and vendors who specialize in high-value foothill properties. Contact us directly at 909-641-8751, and we will connect you with the right people.
Signs of Improvement in the Rancho Cucamonga Insurance Market
Under California’s Sustainable Insurance Strategy, some traditional insurers are beginning to return to fire-prone areas. The state’s “Safer from Wildfires” regulation, per the California Department of Insurance, requires insurance companies to provide you with your wildfire risk score when you apply for a policy, before a renewal or non-renewal, and anytime you complete a mitigation measure and request the updated score. Every action under Safer from Wildfires will qualify you for an insurance discount. The safer your property is from the risk of wildfire, the more you can save.
You also have the right to appeal your risk score directly to the insurance company if you believe it is inaccurate. If the appeal is denied, you can request help from the Department of Insurance by contacting them at 800-927-4357.
Defensible Space and Home Hardening in Rancho Cucamonga
Defensible space is your most powerful tool for both safety and insurability. The determination of fire hazard severity is based on terrain, fire history, weather patterns, and the presence of fire fuels such as thick vegetation, according to CAL FIRE.
Here is how defensible space zones break down:
- Zone 0 (0 to 5 feet from the structure). Create an ember-resistant zone immediately around your home. The statewide Zone 0 regulation is still being finalized by the Board of Forestry, but we recommend treating this as standard practice now. Among the most important mitigations are to create a 5-foot ember-resistant zone around your home, install a Class A fire-rated roof, maintain 6 inches of noncombustible area at the bottom exterior walls, and install double-paned windows, per the California Department of Insurance’s Safer from Wildfires guidelines.
- Zone 1 (5 to 30 feet). This is your lean, clean, and green zone. Remove dead vegetation, space trees and shrubs so they do not create a continuous fuel path, and keep grass mowed to no more than 4 inches.
- Zone 2 (30 to 100 feet). Reduce fuel density. Create horizontal spacing between shrubs and vertical spacing between low vegetation and tree canopies.
Hardening Upgrades That Matter to Insurers
- Class A fire-rated roof
- Ember-resistant attic and foundation vents
- Enclosed eaves with no exposed wood
- Dual-pane tempered windows
- Noncombustible fencing within 5 feet of the structure
- Noncombustible decking or decking with ignition-resistant materials
Even if you think you are not in a hazard area, insurance companies can cancel your policy based on their own criteria, according to California Department of Insurance guidance. Hardening your home puts you in the strongest possible position regardless of zone designation.
For Buyers: Your Pre-Offer Fire and Insurance Checklist in Rancho Cucamonga
Before you write an offer on any foothill home in Alta Loma, Etiwanda, or anywhere north of the 210:
- Confirm the parcel’s FHSZ status on the OSFM map viewer and cross-reference with the Rancho Cucamonga Fire Protection District
- Get an insurance quote from a broker experienced with high-value foothill homes before writing the offer. This is non-negotiable. Build insurance into your total cost of ownership calculation
- Review the Natural Hazard Disclosure report carefully. Look for fire hazard zone designations, flood zones, and earthquake fault zones
- Request defensible space compliance documentation. Under AB 38, this is required for VHFHSZ sales
- Price out hardening upgrades and ask for credits or concessions where the home lacks Class A roofing, ember-resistant vents, or dual-pane windows
- Include an insurance contingency in your purchase agreement. If you cannot secure adequate coverage at a reasonable cost, you need an exit
- Cash buyers: you have no lender mandate for insurance, but you still need adequate coverage to protect an asset worth $1.5M or more. Do not skip this step
For Sellers: How to Protect Your Asking Price in a Rancho Cucamonga Fire Zone
If you are listing a luxury home in Alta Loma or Etiwanda, the insurance conversation is no longer optional. It is part of your pricing strategy. Here is what we tell our sellers with our 46 client reviews at a 4.9 out of 5 rating:
- Get your defensible space inspection and NHD report completed before listing. Do not wait for a buyer to raise the issue
- Document every hardening upgrade with receipts, photos, and contractor invoices. Class A roof installation, vent replacements, landscaping modifications: document it all
- Share your current insurance carrier and annual premium with serious buyers. If you have a policy in place, that is proof the home is insurable, and it removes one of the biggest objections buyers have
- Present mitigation as a value feature in your marketing. A well-hardened, insurable home stands out against comparable foothill listings that have not been upgraded. This is a competitive advantage, not just a safety measure
- Understand the new reality. A home that is difficult to insure sits longer on the market and invites aggressive price negotiation. Homes we sell average 13 days on market because we prepare our sellers for exactly these conversations before the sign goes in the yard
We sell 17% more homes than the average agent in Rancho Cucamonga and we do it 60% faster because preparation is the strategy, not the afterthought.
How Wildfire Risk Affects Long-Term Property Value in the Rancho Cucamonga Foothills
The foothills are not losing their appeal. Alta Loma’s equestrian character, Etiwanda’s newer planned communities near the 15 and 210 corridors, the views, the space: those fundamentals have not changed. What has changed is that an emerging split is developing in the luxury foothill market. Insurable, hardened homes are holding their value and selling with confidence. Uninsurable, unprepared properties are seeing longer market times and heavier negotiation from informed buyers.
Values in Rancho Cucamonga vary widely by neighborhood, from the high $700,000s in the city’s core to more than $1.6 million in foothill communities like Deer Creek, according to current market data. That premium exists because buyers value what the foothills offer. But protecting that premium now requires a new layer of preparation that did not exist five years ago.
Frequently Asked Questions About Wildfire Insurance in Rancho Cucamonga
Is Alta Loma in a Very High Fire Hazard Severity Zone?
Portions of Alta Loma, particularly north of the 210 Freeway and along the San Gabriel Mountain foothills, carry Very High Fire Hazard Severity Zone designations from CAL FIRE. However, designation varies by specific parcel. You should check your property’s individual status using the OSFM map viewer and confirm with the Rancho Cucamonga Fire Protection District at 10500 Civic Center Drive.
How much has homeowners insurance increased in Rancho Cucamonga?
While exact Rancho Cucamonga figures depend on your carrier, property, and risk score, statewide California homeowner premiums have risen approximately 84% since 2020, according to Stanford research. The FAIR Plan specifically approved a 29.1% average rate increase effective October 15, 2026, per the California Department of Insurance, with wildfire-exposed properties potentially seeing much higher increases.
Will the California FAIR Plan cover a $2M or $3M home in the foothills?
The FAIR Plan’s residential dwelling coverage caps at $3.3 million, so it may cover the structure of most foothill luxury homes. However, the FAIR Plan covers only named perils, specifically fire, lightning, smoke, and internal explosion. You will need a separate Difference in Conditions policy or surplus-lines coverage for liability, theft, water damage, and personal property protection.
What is a Difference in Conditions policy?
A DIC policy fills the gaps left by a FAIR Plan policy. It provides coverage for perils the FAIR Plan excludes, such as liability, theft, and water damage. For luxury homes, it is essentially the second half of your insurance package. Work with an independent insurance broker to pair a FAIR Plan policy with the right DIC coverage for your replacement cost.
Can hardening my home lower my insurance premium in Rancho Cucamonga?
Yes. Under California’s Safer from Wildfires regulation, every mitigation action qualifies you for an insurance discount, per the California Department of Insurance. Insurers are required to calculate new rates incorporating these discounts. Key actions include installing a Class A roof, ember-resistant vents

Leave a Reply